What to Do After a Car Accident: Step-by-Step Checklist
Knowing what to do after a car accident protects your health, your claim and your wallet. After a car accident, stop, check for injuries and call 911 if anyone is hurt, move to safety if you can, call the police, exchange insurance and contact details, photograph everything, and report the crash to your insurer. Stay calm and stick to the facts: do not argue about or admit fault at the scene. Get checked by a doctor even if you feel fine, because some injuries show up hours or days later.
Important: this is general information, not legal advice. Accident reporting rules and insurance laws vary by state. If anyone was injured, fault is disputed or the damage is significant, consider speaking with your insurer and a qualified attorney licensed in your state.
What to Do at the Scene of a Car Accident
- Stop and stay calm. Never leave the scene of an accident involving injury or damage; it can be a crime.
- Check for injuries. Call 911 right away if anyone is hurt, unconscious or complaining of pain. Do not move seriously injured people unless there is immediate danger such as fire.
- Make the scene safe. Turn on hazard lights. If the cars can be driven and no one is badly hurt, move them out of traffic to a safe spot, as many states require for minor crashes. Set out flares or warning triangles if you have them.
- Call the police. Ask for an officer to come and write a report, or file one yourself if police do not respond to minor crashes. Get the report number and the officer’s name.
- Exchange information with the other driver(s): full name, phone number, insurance company and policy number, driver’s license number, license plate, and vehicle make, model and color. If the driver is not the owner, get the owner’s details too.
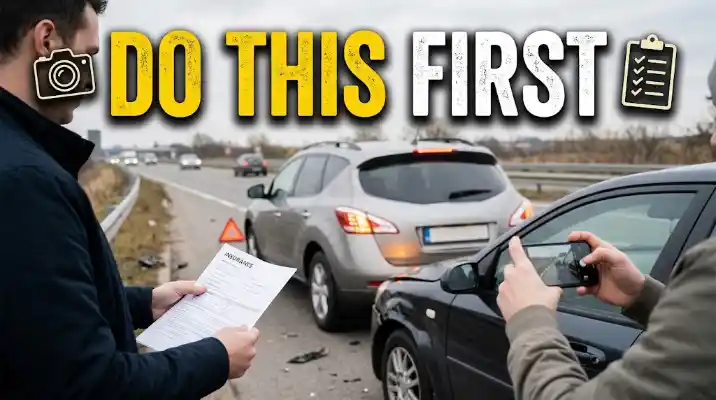
- Document the scene: take photos and video of all vehicles from several angles, the damage, license plates, the overall scene, traffic signs, skid marks, road and weather conditions, and any visible injuries.
- Talk to witnesses: ask for names and phone numbers of anyone who saw the crash.
- Be careful what you say: be polite and factual, but do not admit fault or apologize in a way that sounds like accepting blame. Fault is determined later by insurers and, if needed, courts.
- Write down details while they are fresh: time, location, direction of travel and what happened.
Safety note: if there is fire, smoke, leaking fuel or a risk from traffic, get everyone away from the vehicles to a safe place first. On highways, stay well off the road and behind a barrier if possible while you wait for help. If the car cannot be driven safely, ask for a tow and check what towing costs before you agree to a price.
What to Do in the Next 24–72 Hours
- See a doctor: whiplash, concussions and internal injuries may not show symptoms right away. Medical records also document injuries for your claim.
- Report the accident to your insurer as soon as possible, even if you think the other driver was at fault. Stick to facts and avoid guessing.
- Get the police report once it is available.
- Report to the DMV if required: many states require a report to the motor vehicle agency when there are injuries, deaths or damage above a set dollar amount, often within a few days.
- Start a file: keep photos, the police report, claim numbers, medical bills, repair estimates, rental receipts and notes of every call.
Minor Accidents and Hitting a Parked Car
Minor Fender Bender With No Injuries
For a small crash where everyone is fine, move the cars out of traffic, exchange information and take photos before anyone leaves. Many police departments do not send an officer to minor property-damage crashes, but you can still file a report, and your state may require a DMV report if damage passes a set dollar amount. Settling privately without telling your insurer is risky, because hidden damage or a later injury claim can leave you without coverage.
If You Hit a Parked Car
Stop. Try to find the owner; if you cannot, leave a note somewhere secure on the car with your name, phone number and a brief explanation, and photograph the note, the damage and the scene. Then report it to the police as your state requires. Driving away without leaving your details can be treated as a hit-and-run.
If the Accident Was Not Your Fault
You usually have two paths for getting your car repaired:
| Option | How it works | Pros and cons |
|---|---|---|
| Third-party claim with the other driver’s insurer | Their liability coverage pays for your damage and injuries if they are found at fault | No deductible for you, but it can be slower and they may dispute fault |
| First-party claim with your own insurer | Your collision coverage pays for repairs, minus your deductible | Often faster; your insurer may pursue the other insurer and recover your deductible (subrogation) |
- You can usually choose your own repair shop.
- Ask about a rental car under the at-fault driver’s coverage or your own rental reimbursement coverage.
- In many states you may be able to claim for diminished value, the drop in your car’s resale value after an accident, from the at-fault driver’s insurer.
- Do not sign releases or accept a final settlement until you know the full extent of any injuries and repair costs.
If You Were Hit by an Uninsured Driver or a Hit-and-Run
Call the police immediately and give them any details you have: plate, description, direction of travel. Look for witnesses and nearby cameras. Your uninsured/underinsured motorist coverage may pay for injuries and, in some states, vehicle damage; your collision coverage can also pay for repairs, minus the deductible. Report it to your insurer quickly; many policies require prompt reporting of hit-and-runs.
What Not to Do After an Accident
- Do not leave the scene.
- Do not admit fault or sign anything at the scene other than a police document.
- Do not skip medical care or downplay injuries.
- Do not post about the crash on social media.
- Do not accept a quick cash deal from the other driver to avoid insurance; damage and injuries often cost more than expected.
- Do not give a recorded statement to the other driver’s insurer before you are ready; you can ask to consult your own insurer first.
How Much Does Insurance Go Up After an Accident?
An at-fault accident usually raises premiums noticeably, often for about three to five years depending on the insurer and state. Not-at-fault accidents generally have much less impact, and some states limit rate increases for them. Accident forgiveness programs, offered by some insurers, may prevent a rate increase for a first accident. Shopping around at renewal can help if your rate rises; here is how to switch car insurance without a gap in coverage.
When to Consider a Lawyer
- Anyone was seriously injured
- Fault is disputed or the other insurer denies your claim
- The crash involved a commercial vehicle, rideshare, government vehicle or multiple cars
- The settlement offer does not cover your medical bills or lost income
Many personal injury attorneys offer free consultations. For minor, clear-cut property damage claims, your insurer can usually handle everything.
Keep an Accident Kit in Your Car
- Insurance card and registration
- Pen and notepad, or an accident form
- Phone charger
- Flashlight, flares or reflective triangles
- First-aid kit
- Emergency contact list
Car Accident FAQ
It is wise to get checked within a day or two. Some injuries such as whiplash or concussion show symptoms later, and medical records support your claim.
Call the police, note any details about the other car and look for witnesses or cameras. Uninsured motorist or collision coverage may pay for injuries and damage.
Report it as soon as possible. Most policies require prompt notice, and delays can complicate or jeopardize a claim.
It is usually a good idea, and in many states it is required if anyone is hurt or damage passes a set amount. If police do not come to the scene, you can often file a report afterward, which helps your insurance claim.
Stop, check for injuries and call 911 if needed, move to safety, call the police, exchange information, photograph the scene and damage, then report the crash to your insurer.